Unlock the secrets to homeownership with industry experts on the 'Helping Heroes Become Homeowners' podcast!
Helping Heroes Become Homeowners

YouTube

Oct. 16, 2026

2026-10-16
Yes, I rank everything like a loan. Halloween never stood a chance. Full size bar people, you want one payment for 30 years and you never want to think about it again. Fun size people, you figured out that getting in the door beats waiting for perfect. Candy corn people,…
View more
Oct. 14, 2026

2026-10-14

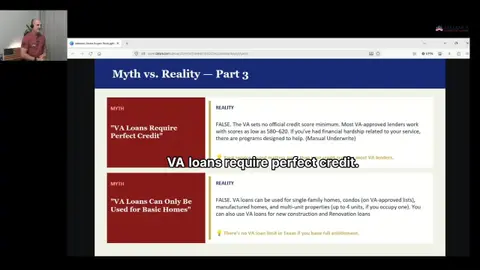
The VA doesn't set an official minimum credit score. For most lenders, a score in the 580 to 620 range is typical for an automated approval. If your credit took some hits, that doesn't automatically mean no. With a manual underwrite, we explain the derogatory credit. If there's a good…

View more
Oct. 12, 2026

2026-10-12

Why Texas is one of the best states for veteran homeowners. 🇺🇸🤠 Texas is a tax-friendly state. We don't pay state income tax, only federal. Yes, our property taxes run a little higher. But if you're a 100% disabled veteran, you're exempt from property taxes in Texas. Not every state…

View more
Oct. 9, 2026

2026-10-09

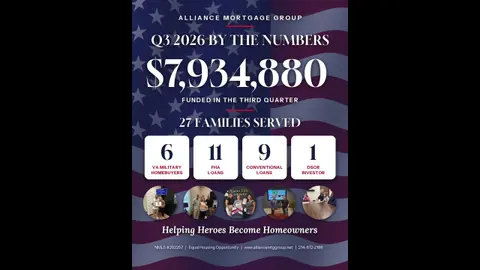
27 families. $7,934,880 funded. One team. Q3 2026 is in the books, and I couldn’t be prouder of the Alliance Mortgage Group team. These numbers took our loan officers, processors and support staff working together. That meant late-night pre-approvals, weekend calls with nervous first-time buyers, and chasing down the last…

View more
Oct. 8, 2026

2026-10-08

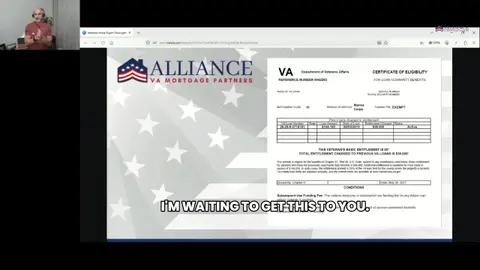
See "Funding Fee Exempt" on your COE? You don't pay the VA funding fee. 🇺🇸 Comment "EXEMPT" and I'll pull your Certificate of Eligibility to check. NMLS #291309

View more
Oct. 7, 2026

2026-10-07

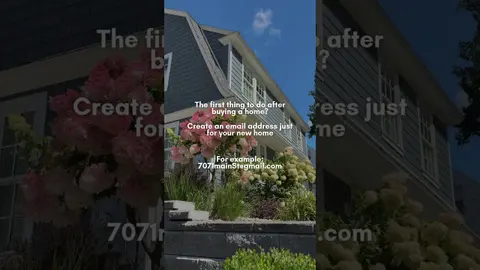
Why? Your mortgage statements, escrow notices and homeowners insurance renewals all land in one place. Your closing documents, appraisal and inspection report are one search away, which you’ll want if you ever refinance. Property tax bills, utility accounts and appliance warranties stay organized from day one. Contractor quotes, invoices and…

View more
Oct. 6, 2026

2026-10-06

Think you qualify for a VA loan? Don't assume it. Check first. 🇺🇸 Comment "COE" and I'll pull your Certificate of Eligibility before you start house hunting. NMLS #291309

View more
Oct. 5, 2026

2026-10-05

High debt-to-income ratio? Don't count yourself out on a VA loan. 🇺🇸 VA doesn't have a hard DTI cap. When you're over 41%, what matters is your residual income, the money left over each month after your bills. If your residual exceeds VA's guideline by 20%, your income is stable,…

View more
Oct. 4, 2026

2026-10-04

VA loans = higher approval rating + 100% financing. Putting $0 down doesn't hurt your chances. 🇺🇸 Comment "VA" and I'll show you what you qualify for. NMLS #291309

View more
Oct. 3, 2026

2026-10-03

Some conventional loans actually offer slightly better interest rates when buyers put less than 20% down. Here’s the strategy you may want to consider: • Buy with 5–15% down • Lock in the lower interest rate • After closing, recast the loan A recast lets you put a lump sum…

View more
Oct. 2, 2026

2026-10-02

It’s not a trick question. It’s just a question with one answer. Pay stubs tell me what you earn. Bank statements tell me where the down payment is coming from, and that it’s been sitting there minding its own business. Different jobs, both required, no hard feelings. – If we…

View more
Oct. 2, 2026

2026-10-02

It is easy to feel stuck when rates are the loudest part of the conversation. But rates are not the only part of buying a home. There is also the payment you can actually handle, the neighborhood you want to live in, the amount of space you need, and the…

View more
Oct. 2, 2026

VA Loan Benefits: Why You'll Never Pay PMI

Most homebuyers pay private mortgage insurance (PMI) every month until they reach 20% equity. With a VA loan, you never pay it. In this video, I break down how much that saves you. A conventional buyer can pay $150–$250 a month in PMI for 5–8 years, adding up to $9,000–$24,000…

View more
Oct. 1, 2026

2026-10-01

Here is the part buyers are rarely told at the dealership. Mortgage approval looks at monthly debt, not just whether you can afford the car today. A new car payment can raise your debt ratio, lower the home price that fits, or change the loan options available to you. The…

View more
Sept. 30, 2026

2026-09-30

Buying the home is only part of the budget. You also need to think about what happens after closing. Furniture can wait. Cosmetic upgrades can wait. Big purchases on credit should be handled carefully, especially before closing. And your emergency fund should not disappear just because the house needs a…

View more
Sept. 29, 2026

2026-09-29

If you are renting and wondering whether buying is even realistic, here is how I would look at it with you. First, we would look at your actual numbers, not internet guesses. Income, credit, debts, savings, and the kind of monthly payment you could live with. Then we would separate…

View more
Sept. 28, 2026

2026-09-28

Your pre approval can be current on paper and outdated in practice. Before your next offer, run this 15 minute refresh: 1️⃣ Check the letter Find the issue date and any expiration date. Ask your lender what becomes stale first for your loan: credit, income, asset statements, or the letter…

View more
Sept. 26, 2026

2026-09-26

Here is the friendly version of the debt conversation. Lenders look at required monthly payments. So a car payment or other debt can reduce the room available for a housing payment. But there is no universal rule that $850 of debt always equals $100K of buying power. We have to…

View more
Sept. 25, 2026

2026-09-25

Ever wondered how to make your VA loan process WAY smoother? 👀 It all starts with ONE document most veterans forget about — your Certificate of Eligibility (COE). 📄 Without it, lenders literally can't confirm you're eligible for a VA loan. Good news: you don't have to dig anything up.…

View more
Sept. 24, 2026

2026-09-24

Many veterans fear that one collection or a past credit issue will automatically kill their VA loan. It won't — here's why. 🇺🇸 First, your loan runs through an automated underwriting system (like DU or LPA). It checks your credit, debt, income, and history. If it comes back "refer" instead…

View more
Sept. 23, 2026

2026-09-23

View more
Sept. 20, 2026

2026-09-20

Some people count sheep. You scroll listings and calculate imaginary mortgage payments. 😂 If a 1:00 AM listing has you thinking, “Wait… could I actually afford this?” remember that the price on the screen is only part of the answer. Your payment can also include the interest rate, property taxes,…

View more
Sept. 19, 2026

2026-09-19

This might be an unpopular opinion 👀 ratios are NOT the whole story on a VA loan. Most loans (FHA, Conventional, USDA) live by your debt-to-income ratio. VA loans? Different game — it's about RESIDUAL INCOME. That's what's left after mortgage, debts, taxes, childcare, commuting... everything. 65% debt ratio and…

View more
Sept. 19, 2026

2026-09-19

When a seller offers money, I want buyers to answer one question first: where does the money solve the biggest problem? A lower price can reduce the loan amount A closing cost credit can protect cash A rate reduction may lower the monthly principal and interest payment if the loan…

View more